

Living with an overspending spouse can leave you worrying about bills, savings, and whether you can trust the next purchase. Start by identifying what the spending is affecting, discussing the numbers calmly, and agreeing on changes both partners understand.
Different priorities do not automatically make someone irresponsible. The concern becomes more serious when purchases repeatedly undermine essential expenses, agreed goals, or financial security. You can address those consequences while respecting your partner’s independence.
What Counts as Overspending in a Marriage?
Here, overspending means spending beyond what your household can afford or repeatedly breaking a spending agreement. It is not simply buying something the other person dislikes. Before judging individual purchases, check whether your budget covers realistic living costs. Groceries, healthcare, childcare, and work expenses can rise without either partner becoming careless. An income shortfall needs a different response from repeated unplanned shopping.
Ask what has changed: the amount spent, the frequency, the borrowing, or the secrecy. If rent, food, utilities, or medicine are already at risk, identify the amounts and dates needed to keep them covered.
Important: Joint planning assumes you can disagree safely. If money discussions involve threats, intimidation, or restricted access to necessities, seek confidential support before attempting a confrontation.
7 Ways to Address the Problem Together
Helping an overspending spouse involves understanding the pattern, setting workable limits, and following through. Start with the steps that address your immediate concern; missed essential bills deserve attention before a debate about small treats.
1. Establish the Facts Before Assuming the Cause
Review a recent month or two of spending together, including subscriptions, debt payments, installment purchases, cash withdrawals, and irregular expenses. Include both partners’ spending and future payments already committed. Look for specific patterns. Are several small purchases accumulating? Is one person covering household costs, and does the other never see it? Did spending increase after a stressful period or a change in income?
Ask, “What tends to happen before you buy something you later regret?” Listen without deciding in advance that shopping means boredom, an unhappy marriage, or a mental health condition. Understanding the context helps you choose a response. Each person remains responsible for their behavior. You can set financial boundaries while the reasons are still being explored.
2. Have a Specific, Respectful Money Conversation
Choose a calm time when neither of you is rushing. Use assertive communication to explain the concern and request a concrete next step.
For example: “Our unplanned purchases totaled 300 this month, and we are short on rent. Can we review what happened and decide how to cover the gap?”
That gives you something measurable to discuss. Avoid labels such as “shopaholic”, “selfish”, or “bad with money”. Practice listening before responding, including when you disagree. You might discover missing expenses or different assumptions about what counts as shared money. If the discussion becomes heated, suggest a pause and agree when to return. Respectful language matters, but you are not responsible for making another adult honest by choosing perfect words.
3. Build a Budget That Reflects Your Actual Household
A plan for an overspending spouse needs realistic amounts, clear responsibilities, and room for everyday life. Start with take-home income and essential expenses, then include debt payments, savings where affordable, and irregular costs. Use your own figures rather than treating a budgeting percentage as compulsory.
| Budget area | What to agree |
| Essentials | Amounts needed and payment dates |
| Debt | Balances, minimum payments, and repayment priorities |
| Irregular expenses | Provision for repairs, annual bills, and celebrations |
| Shared goals | An affordable contribution and review date |
| Personal spending | Money each person can use without purchase-by-purchase approval |
Choose financial goals as a couple, while recognizing unpaid caregiving and household work. Earning less should not remove someone’s voice in decisions or access to necessities. If essentials exceed income, the budget is showing a shortfall. Seek help with affordability rather than assuming stricter shopping rules will solve everything.
A hypothetical example: Suppose monthly take-home income is 3,000 and planned bills, debt payments, savings, and personal spending total 2,900. An unplanned purchase of 250 creates a 150 shortfall. Agree on how to cover that gap and prevent a repeat. If the budget already totals 3,200, the household has a wider affordability problem before any extra purchase.
4. Agree on Purchase Rules Before the Next Temptation
Decide which purchases need discussion and which fall within personal spending money. The same agreed principles should apply to both partners. For example, you could discuss unplanned purchases above an affordable threshold, record installment commitments in the budget, and pause before optional purchases outside the plan. A 24-hour pause is one possible arrangement, not a scientifically established treatment. Choose something you can both follow, with exceptions for urgent needs.
Write down what happens when a limit is exceeded: review the shortfall, consider a return where possible, and adjust the remaining spending together. Keep discussion thresholds separate from personal spending money. Within the agreed personal budget, neither partner should need approval for every purchase. Necessary food, medicine, and transport must remain accessible.
5. Choose Payment and Account Safeguards by Agreement
Agree on safeguards that protect household commitments while preserving access to necessities. Avoid confiscating your partner’s cards or taking control of all their money. Instead, discuss options such as purchase alerts, removing saved payment details from shopping sites, or using a separate account for agreed discretionary spending. A cash envelope may suit some purchases, but it does not guarantee better decisions.
You may choose joint accounts, separate accounts, or a combination. Both partners need access to necessary information and funds under that agreement. Check balances before scheduling automatic payments. Destroying a card does not close its account or cancel existing debt. You can seek independent advice about protecting your own accounts or challenging unauthorized borrowing. Ask the provider about your options before changing arrangements. Liability depends on account ownership, borrowing terms, and local law.
6. Review Progress Without Becoming a Parent or Monitor
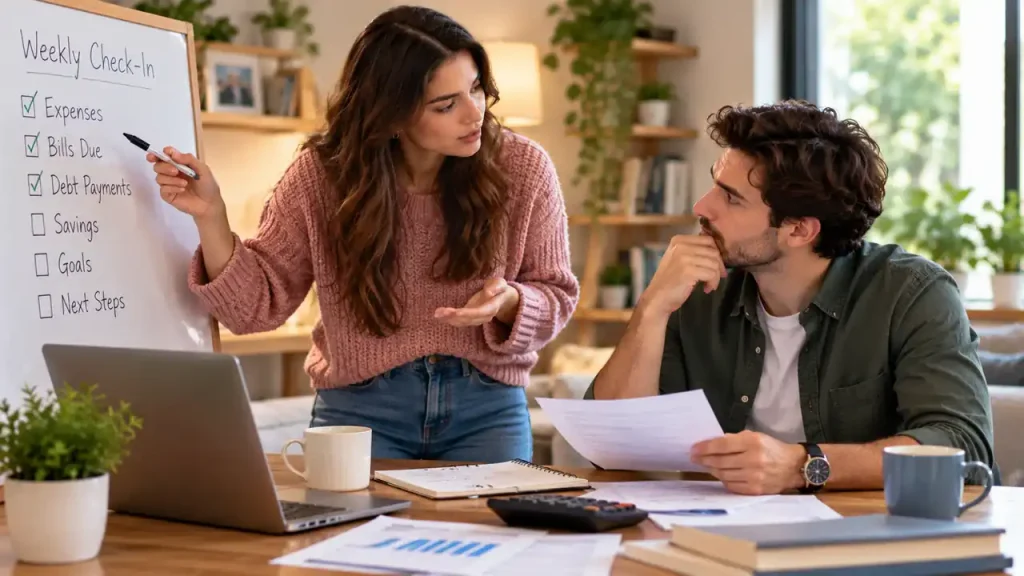
A plan with an overspending spouse needs follow-up. Try a short weekly check-in initially, then adjust the frequency to your circumstances. Discuss what was spent, which bills are due, whether new borrowing occurred, and what needs changing. Use agreed records rather than secret surveillance.
Acknowledge specific progress: “We stayed within our personal budgets and paid the bill on time.” Appreciation works best as recognition between equals, rather than rewards one adult grants another for obedience.
If an agreement is broken, address the impact and the next action. Apologies and reassurance in relationships need matching actions; another promise alone does not show that the plan is working. When money conflict has damaged trust, repairing the relationship also requires consistent behavior and willingness to participate.
7. Get the Right Help When the Pattern Continues
Different problems call for different support. A qualified debt or credit counselor can help assess bills, borrowing, and repayment options. Before signing up, check qualifications, charges, and written terms using these questions for choosing a credit counselor. Nonprofit status does not automatically mean every service is free.
Persistent buying urges, repeated unsuccessful attempts to stop, and substantial distress or harm warrant a mental health assessment. A 2021 expert consensus study on compulsive buying proposed features including impaired control and continuing despite negative consequences. These can prompt professional assessment; they are not a home diagnostic checklist. A couples therapist may help with recurring conflict when both partners can participate freely and safely. You can also seek individual advice if your partner refuses help.
Distinguish Overspending, Secrecy, and Financial Abuse
These problems can overlap, but they need different responses. Overspending concerns affordability and agreements. Financial infidelity involves deception about money that violates the couple’s financial understanding, such as concealed borrowing that affects shared obligations. Neither is an inevitable consequence of the other.
Financial abuse involves power and control. Examples include taking a partner’s earnings, preventing access to money, or using financial restrictions to control everyday life. These signs of financial abuse explain why some situations need confidential support rather than a shared budgeting exercise. Personal financial privacy and funds kept for safety should not automatically be labeled dishonesty. If you fear retaliation, seek confidential advice from a local domestic abuse service or an appropriate legal professional.
Common Questions
1. Should I Pay Off My Partner’s Debt?
Pause before committing. Establish the balance, interest, ownership, and whether borrowing is continuing. Taking on another loan without understanding the situation may increase your exposure. Get advice before signing, guaranteeing, or consolidating debts.
2. What if My Partner Refuses to Discuss Money?
State the practical issue and your boundary clearly: “I cannot agree to new shared borrowing without understanding the existing balances.” Obtain independent advice about your accounts and obligations. Threats or intimidation require a safety-focused response.
3. How Soon Can an Overspending Spouse Change?
There is no universal deadline. Look for observable changes: accurate information, participation in the plan, fewer broken agreements, and bills being addressed. More serious debt or compulsive behavior may need sustained professional support.
Final Thoughts
Dealing with an overspending spouse takes honest conversations, realistic agreements, and consistent follow-through. Start with the financial concern causing the most strain, protect essential expenses, and agree on changes you can both maintain. Each partner deserves a voice in decisions and access to necessities. If broken agreements or hidden borrowing continue, seek qualified support. You can support your partner’s efforts, but you cannot take responsibility for their choices or rebuild financial trust alone.

Leave a Reply