

Money management tips help newlyweds answer ordinary questions: Who pays the rent? Can either partner buy something without checking first? What happens if one of you loses income? Marriage brings shared decisions, but it does not require identical spending styles or a single bank account. The goal is to know what you owe, protect essentials, and agree on a process that treats both partners fairly. These eight steps help you start conversations before money becomes a recurring argument.
Why Money Conversations Matter After Marriage
One person may feel secure when savings grow; the other may prefer travel, gifts, or helping relatives. Neither preference automatically makes someone irresponsible. Trouble begins when expectations remain unspoken or one spouse makes decisions that affect both without discussion. The honeymoon phase can reveal different financial backgrounds. Discuss these differences with curiosity. A partner who grew up with irregular income might value a larger cash buffer; someone who watched relatives struggle with debt may feel anxious about credit cards. Understanding those preferences makes decisions easier.
Eight Practical Steps for Managing Money Together
These money management tips are a starting framework, not rules that every couple must follow. Choose arrangements that suit your income, caregiving, values, and local banking laws; revisit them when circumstances change.
1. Share Your Financial Starting Points
Pick a calm time and compare take-home income, debts, minimum payments, savings, regular bills, and financial commitments to family members. Include irregular earnings and existing obligations. You do not need to exchange passwords to understand each other’s financial position. You do need enough information to avoid surprises when applying for credit or planning housing costs.
Try asking, “What money responsibility worries you most this year?” Then listen to the answer before correcting it. Being a good listener can make these sensitive conversations more productive. Discuss existing debt without assuming it automatically becomes the other person’s legal responsibility; liability depends on account agreements and local law.
2. Agree on Two Goals, Not Ten
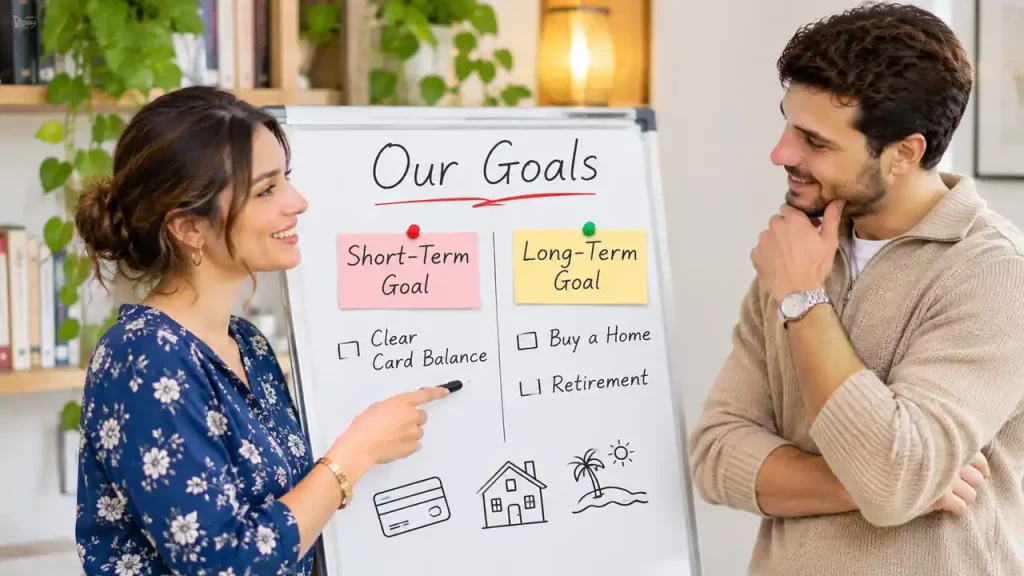
Choose one near-term priority, such as clearing a costly card balance or saving for a move, and one longer-term goal, such as education, a home, or retirement. Write an approximate cost and a realistic date. If a trip matters to both of you, plan it instead of treating every enjoyable expense as wasteful.
For example, a $1,200 goal over twelve months means setting aside $100 monthly, if your cash flow permits. If it does not, extend the deadline rather than borrowing to meet an arbitrary target. Shared goals work best when each person still has room for individual interests and meaningful reassurance in the relationship.
3. Build Your Budget From Real Spending
Review two or three months of transactions and record take-home pay, essential bills, minimum debt payments, irregular costs, savings, and optional purchases. Reviewing actual spending records and including infrequent expenses can give you a more reliable picture than relying on estimates alone.
Put payment dates beside amounts: a bill arriving before payday can create trouble even when monthly income looks sufficient. For instance, if your combined take-home pay is $4,500 but $3,700 already goes to necessities and required payments, there is $800 to allocate among future bills, discretionary spending, and savings. Do not assign that $800 twice. Useful money management tips account for actual cash flow, not only percentages.
The 50/30/20 split can inspire a first draft, but it is not mandatory or feasible for every household. If necessities consume most income, prioritize those first. Identifying bad spending habits can help you adjust discretionary purchases without blaming each other for rising essential costs.
4. Split Household Costs in a Way That Feels Fair
An equal split is simple, but not always workable. Suppose one partner takes home $4,000 monthly and the other $2,000. If they agree to contribute in proportion to income, the first covers two-thirds of shared bills and the second one-third. On $2,100 of shared costs, that is $1,400 and $700. These are examples.
Count unpaid caregiving and domestic work when discussing fairness. If one partner reduces paid work to care for a child or relative, revisit contributions and access to personal money. Different approaches to sharing finances after marriage include joint accounts, separate accounts, and contributions based on income. Choose an arrangement together; do not let income determine whose opinion counts.
5. Choose Joint, Separate, or Hybrid Accounts
A joint account can simplify household bills. Separate accounts can preserve independence. A hybrid arrangement uses a shared account for agreed expenses and individual accounts for personal spending. None is proof of greater love or trust. Before opening a joint account, confirm who can withdraw money, close it, incur fees, or access overdrafts under your bank’s terms. In some systems, either owner can withdraw the entire balance without the other’s approval. Ask about account alerts, authorized users, and contingency access.
Decide who deposits money, who checks balances, and what happens if earnings change. Keep both partners informed even when one enjoys bookkeeping more. Review account protections with your own bank because deposit insurance and account-ownership rules differ between countries.
6. Protect Privacy Without Hiding Financial Risks
Agree on a threshold for discussing purchases from shared money. A couple might choose $150; another might choose $500. Each person can also have an affordable personal allowance without defending every small receipt. Privacy is compatible with honesty. Concealing major debts, opening credit in a spouse’s name, or lending shared savings without agreement is different from buying a birthday gift privately.
When discussing sensitive financial matters, starting with manageable money conversations and focusing on shared goals can make it easier to understand each other’s expectations without turning the discussion into an argument.
When dealing with an overspending spouse, it helps to discuss how purchases affect shared responsibilities rather than attacking personal habits. Practicing assertive communication can make those discussions more constructive. Restricting a partner’s access to necessities, coercing debt, or monitoring every transaction may be financial abuse; seek independent, confidential support when safety is in question.
7. Prepare for Emergencies and Planned Big Bills
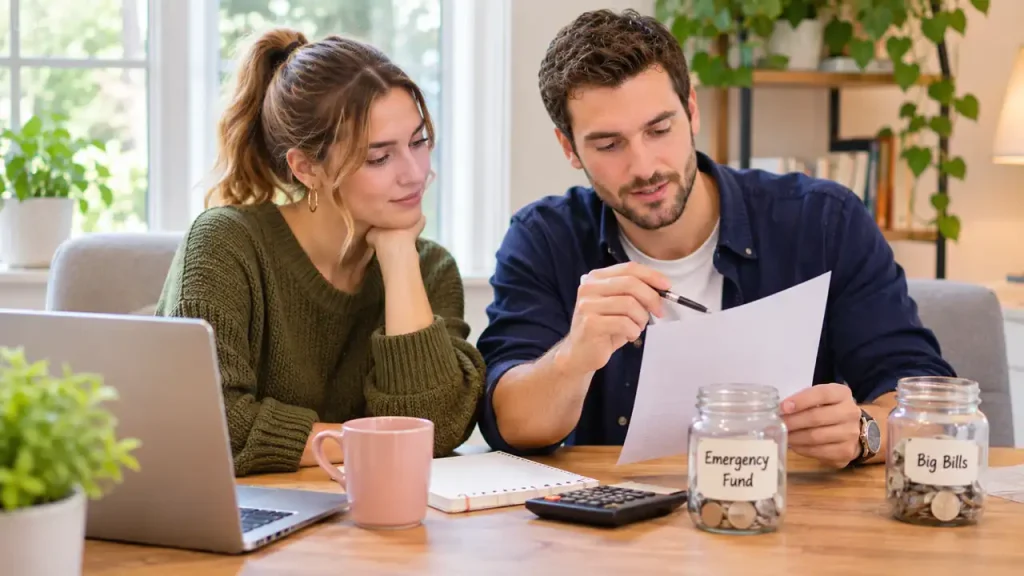
Keep two categories: predictable expenses and emergencies. Annual insurance renewals, gifts, school fees, and vehicle servicing belong in a planned-expense fund. Unexpected medical expenses, urgent repairs, or income loss may require emergency savings. Start with an affordable amount and keep emergency money accessible. Using it for a genuine emergency is the point; rebuild it when possible. If high-interest debt is already costly, discuss whether to build a modest starter reserve while prioritizing required payments and affordable extra repayments. Avoid investing money you may need for next month’s rent.
Review insurance already available through employers before paying for extra policies. Understanding different insurance policies can help you compare coverage, costs, exclusions, and beneficiaries. If children may be part of your plans, estimate childcare and parental-leave costs early. Developing a realistic approach to saving money for kids can also become part of your longer-term financial discussions.
8. Share the Work and Hold a Monthly Money Date
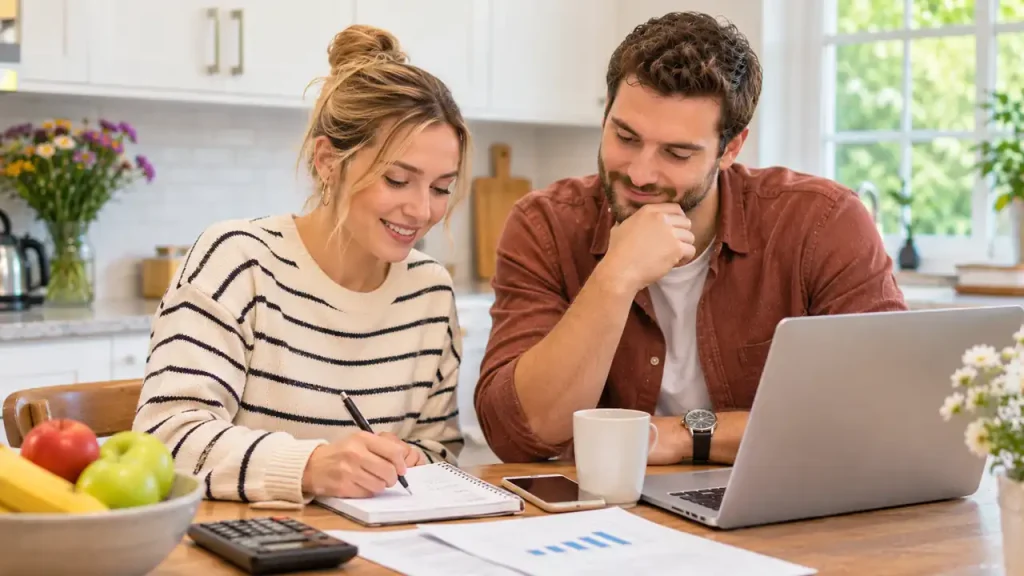
Someone needs to check renewal dates, pay utilities, monitor subscriptions, and update the budget. Divide these tasks by capacity and preference, not by gender. Both spouses should know where essential records are and how bills are paid. Following a practical healthy eating plan may also help coordinate grocery decisions, without assuming home cooking is always cheaper.
Once a month, ask:
- What went well?
- What surprised us?
- What should change?
Keep the meeting to twenty minutes and agree on one action. These money management tips should make life calmer, not turn dinner into an audit. Check in again after a job change, family emergency, or new caregiving responsibility.
Your First Month: A Simple Shared-Money Plan
Use this four-week sequence to spread decisions out. Record agreements without sharing passwords or sensitive account numbers.
| Week | What to discuss | Outcome |
| 1 | Income, debts, bills, and due dates | A shared financial picture |
| 2 | Bill contributions and account access | Clear responsibilities |
| 3 | Savings, personal money, and purchase limits | A workable agreement |
| 4 | Unexpected costs and first-month results | One adjustment for next month |
A written agreement is a reminder, not a legal contract. Revisit it whenever it no longer fits. If one spouse feels uneasy about an arrangement, ask which part seems unfair and test a change for a month before making it permanent. If essential expenses exceed income, consider payment arrangements, benefits, additional income, or reputable debt support rather than making the budget look balanced on paper.
Frequently Asked Questions
Couples often have practical questions after the first budget discussion. The answers depend on account terms, household needs, and how safely both partners can make decisions.
1. Should Newlyweds Combine Every Bank Account?
No. Joint, separate, and hybrid accounts can all work. Review access rights, fees, and responsibilities before changing how money is held.
2. Is Splitting Bills Fifty-Fifty Always Fair?
Not necessarily. Income-based contributions and unpaid caregiving may matter. Revisit the split when earnings or family needs change.
3. What if My Spouse Avoids Every Money Conversation?
Start with one small bill and a short, scheduled discussion. If avoidance is paired with threats, coerced borrowing, or control of essentials, prioritize safety and confidential advice over negotiating alone.
Final Thoughts
The best money management tips are not about watching every purchase or merging every account. They are about sharing accurate information, making fair agreements, maintaining individual dignity, and adjusting when life changes. Building a happy marriage takes care beyond a spreadsheet, but a calm monthly money conversation can make everyday responsibilities less stressful. Start with one bill, one goal, and one honest discussion; build from there.


The article is very well written, I agree using Life Skills to Improve the Lifestyle is important for a longer period of time, monitoring and controlling is equally important especially the current global situation. Cheers.