

Women entrepreneurs may encounter funding barriers, unequal caregiving demands, gender bias, limited access to customers, and gaps in useful business support. These challenges can overlap, but their impact varies with location, industry, income, disability, family circumstances, and the stage of the business.
A promising idea still needs paying customers, workable costs, and enough time to deliver. This guide explains five common obstacles and practical ways to assess your next move. Confidence can support action; fair access, reliable information, and appropriate professional help matter too.
Why These Challenges Need More Than Determination
Research on barriers to business finance, published in 2025, describes gender bias, unequal access to property, unpaid work, and differences in access to education and networks. It also emphasizes that business size, sector, and national context affect financing needs and opportunities.
Women entrepreneurs need support that fits their business. A retailer looking for money to cover everyday costs faces different decisions from a technology founder offering investors an ownership stake. Their sector, resources, and plans need individual assessment, without stereotypes about courage or capability.
Five Challenges at a Glance
Start with the issue currently limiting your business. Trying to solve everything at once can scatter limited time and money.
| Challenge | A useful first action |
| Funding and cash flow | Calculate what you need, when, and why |
| Care responsibilities and time | Review the workload and arrange specific support |
| Bias and credibility | Prepare evidence and clear professional terms |
| Customers and commercial networks | Test demand with a defined customer group |
| Skills and advisory support | Find help for one concrete business decision |
1. Securing Suitable Funding and Managing Cash Flow
For women entrepreneurs, financing barriers may include limited collateral, unsuitable financial products, biased assessments, or difficulty reaching investors. However, borrowing is not the right solution for every business or every cash shortage. Begin with a startup-cost calculation. Separate one-time expenses from recurring bills, and include stock, equipment, permits, software, insurance, professional services, and the time between paying suppliers and receiving customer payments.
Check the economics of each sale. In a hypothetical example, a product sells for $50 and has $30 in variable costs. The remaining $20 must contribute toward fixed costs and any profit; it is not automatically take-home pay. Also map payment timing. If materials must be paid for today but a customer pays after delivery, you need cash to bridge that gap. Discuss clear deposit or milestone terms where appropriate, and include refunds, delays, and cancellation obligations in your planning. Before accepting finance, compare repayment schedules, total charges, collateral, personal guarantees, and any ownership or decision-making rights involved. Understand what happens if sales arrive later than expected. Seek qualified advice when terms are unclear.
Ask yourself: “Is this money funding demand I have tested or covering a problem with pricing, costs, or collections?” A smaller pilot may help you learn before committing more capital. Higher risk does not guarantee higher returns.
2. Managing Care Responsibilities and Limited Time
Business ownership can offer some control over scheduling, but customers, suppliers, and employees still create deadlines. Working from home also does not provide childcare or make household work disappear. Look at your actual week. Include care appointments, travel, administration, customer work, household planning, and rest. The difficulty may be insufficient support rather than poor organization. Where possible, discuss how your family shares responsibilities. Replace “I need more help” with a specific arrangement: “Can you handle school collection on Tuesdays and Thursdays while I meet clients?” Include the planning behind tasks, not just their execution.
If you live alone, care for relatives, or lack dependable support, consider what capacity your business can realistically sustain. That may mean fewer service hours, a smaller product range, or paid assistance when affordable. Review arrangements when circumstances change. Sustainable operations should not depend on one person being permanently available, and exhaustion is not evidence of entrepreneurial commitment.
3. Handling Gender Bias and Establishing Credibility
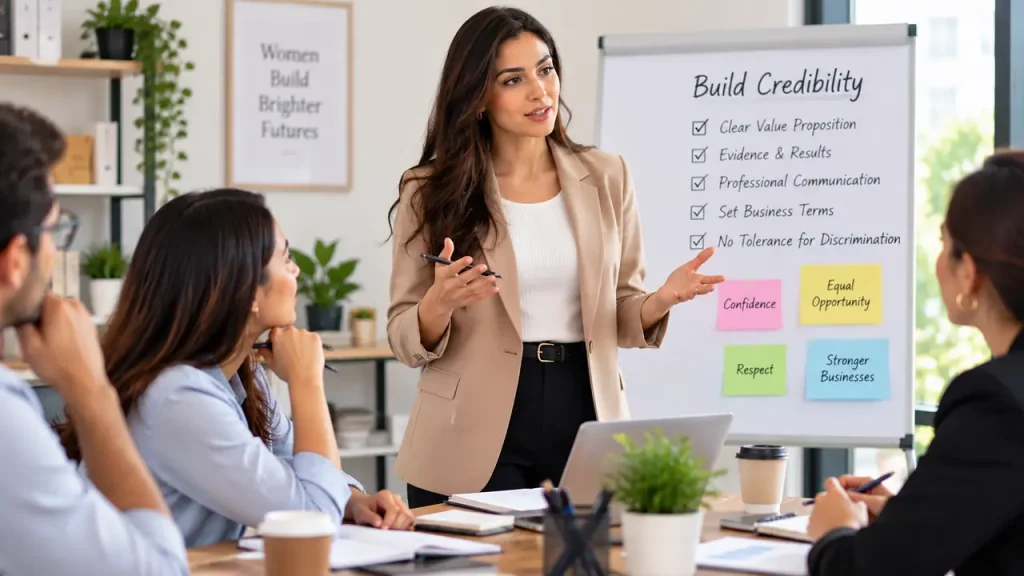
Bias may appear when someone questions your authority, directs decisions to a male colleague, or assumes your business is a hobby. Preparing well can strengthen a proposal, but it cannot make you responsible for another person’s discrimination. Create a concise explanation of your offer: who you serve, what problem you address, how you deliver, and what evidence you have. Use relevant qualifications, completed work, customer feedback shared with permission, or documented results. Avoid impressive claims you cannot substantiate.
Practicing public speaking can make a pitch clearer. You can rehearse without waiting to feel completely confident. Use assertive communication to set business terms: “The proposal covers these deliverables. Additional work requires a revised quote.” Written scope, payment terms, and decision-making responsibilities can reduce ambiguity. Harassment or intimidation requires more than a polished response. Preserve relevant records when appropriate, consider your safety, and seek useful local advice or reporting support. You do not have to tolerate mistreatment to retain a customer, investor, or professional contact.
4. Reaching Customers and Useful Commercial Networks
Access to introductions, buyers, distributors, and procurement opportunities can affect which businesses get noticed. A large social following is not a substitute for understanding who will buy and why. Define one customer group and a specific need. Ask potential customers what they currently use, what frustrates them, and what influences their buying decision. Being a good listener helps you hear objections instead of treating every conversation as a sales pitch.
When feasible and lawful, test a limited offer with clear terms. Track inquiries, actual purchases, delivery costs, repeat business, and reasons people decline. Compliments alone do not establish demand. Build relationships deliberately. Choose a relevant trade group, supplier event, local business association, or buyer meeting rather than collecting contacts indiscriminately. Use thoughtful follow-up questions to understand the other person’s work before requesting an introduction.
For a larger buyer, ask about supplier requirements, order sizes, payment timing, and application procedures. Check whether you could afford and deliver the order before treating it as a breakthrough. Growth can increase working-capital needs as well as revenue.
5. Finding Relevant Skills, Mentors, and Professional Support
Founders do not need to know everything, but they do need a way to identify gaps and obtain reliable help. Training is useful when it improves a decision you are currently facing. For women entrepreneurs choosing a mentor, relevant experience matters more than an impressive title. Ask whether they understand your business model, customer market, and current stage. A mentor can discuss options; an accountant, lawyer, or other appropriately qualified professional may be needed for specialist work.
Make your request specific: “Could you review the assumptions in my pricing?” is more useful than “Tell me how to become successful.” Bring your figures, explain the decision, and ask about fees, confidentiality, and potential conflicts of interest.
In the United States and its territories, women’s business support centers offer counseling and training. Check local services and eligibility. Elsewhere, investigate official enterprise agencies, credible incubators, chambers of commerce, and relevant professional associations. Before paying for coaching, request clear deliverables and terms. Guaranteed funding, effortless profits, and pressure to buy immediately are reasons to investigate carefully. Advice should help you evaluate evidence, not replace your judgment with dependence on a coach.
What Supporters and Institutions Can Change
Practical improvements could include clearer funding criteria, accessible networking events, and training with published costs and eligibility. Business associations can offer relevant buyer introductions, while lenders and investors can review assessment processes for bias. Partners and relatives can share care responsibilities and respect working hours. These changes address access and workload alongside individual preparation.
Turn the Advice Into a Four-Week Plan
Use this as a planning example, adjusting it to your circumstances:
- Week one: List the obstacle causing the most difficulty and gather the relevant numbers or records.
- Week two: Speak with potential customers, a suitable adviser, or the people involved in a practical support arrangement.
- Week three: Test one manageable change, such as a revised offer, clearer payment terms, or a different division of tasks.
- Week four: Review what happened. Compare the results with the time, cost, and effort involved, then decide whether to continue, adjust, or stop.
The purpose is to improve a decision. Four weeks is not a deadline for launching, securing investment, or becoming profitable.
Common Questions
1. What Is the Biggest Challenge for Women Entrepreneurs?
Access to suitable finance is a significant documented barrier, but the most pressing issue varies. For one founder, it may be childcare; for another, customer demand, payment delays, or restrictive local conditions. Identify your actual constraint before choosing a solution.
2. Does Every Business Need Outside Investment?
No. Funding needs depend on the business model, costs, timing, and growth plans. Savings, business revenue, borrowing, and equity involve different trade-offs. Compare realistic options without assuming that raising investment is the measure of a successful business.
3. Should Fear of Failure Stop You From Starting?
Concern about losses can prompt useful preparation. Define what you can afford to risk, test assumptions, and decide in advance what evidence would make you change course. Pausing or rejecting an unworkable idea can be a sound business decision.
Final Thoughts
Women entrepreneurs deserve fair access to finance, markets, skills, and support. Start with the obstacle affecting your business now, gather evidence, and choose a manageable next step. Share responsibilities where possible, use qualified advice when needed, and review whether your plans remain workable. Progress depends on resources, decisions, and opportunity alongside determination; success should never require accepting discrimination or risking more than you understand.


Leave a Reply